Key Insights
- Fintechs are acquiring banks to gain charters, deposits, and infrastructure faster than building from scratch.
- CFIs with strong deposit franchises, lending relationships, and sound compliance records may attract fintech interest.
- Understanding your institution's strategic value can help management evaluate and prepare for a range of outcomes.
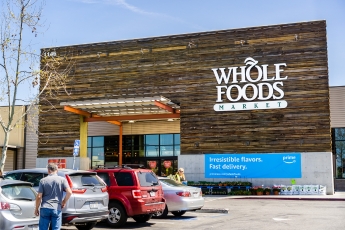
When Amazon wanted to expand into grocery, it bought Whole Foods for $13.7B, gaining more than 460 stores, an established customer base, and an operating business it could integrate with its technology and logistics capabilities. The deal illustrates the potential appeal of buying an established platform rather than building every component from the ground up.
As technology companies move further into financial services, some are considering whether acquiring a financial institution could provide a faster route to scale than developing a banking operation themselves — a strategy that is becoming more viable as regulators show greater openness to new banking models.
For community financial institutions (CFIs), this creates a new strategic consideration: could fintechs become another potential source of acquisition interest, alongside traditional bank buyers?
Why Fintechs Are Pursuing Bank Acquisitions
For fintechs, acquiring an existing bank can provide faster access to a charter, payment infrastructure, deposits, lending capabilities, and established regulatory processes without having to build everything from scratch. Several recent transactions show how fintechs are using bank acquisitions to gain capabilities that would take time to build independently.
- In 2025, SmartBiz acquired $148MM-asset CenTrust Bank as part of its strategy to expand small-business lending nationwide. The acquisition gives the fintech greater control over funding and lending by providing access to its own deposit base and balance sheet, while reducing its dependence on third-party bank partners.
- More recently, Increase acquired Twin City Bancorp, a $70MM-asset CFI with a single branch, and relaunched it as Increase Bank, nearly doubling its asset size. The institution was large enough to provide established banking infrastructure, but small enough to avoid a significant branch network or legacy balance sheet to unwind, giving Increase a relatively simple platform for its technology-driven model.
- In June this year, digital lender OppFi agreed to acquire BNCCORP, a $1.1B-asset bank, to gain a national bank charter, extensive deposit base, and established lending relationships. If approved, the deal will allow OppFi to originate loans on its own balance sheet while bringing its digital capabilities to BNCCORP’s operation.
What Makes CFIs Attractive to Potential Buyers?
A CFI’s value to a fintech may extend well beyond its charter. Here are some of the characteristics that make a CFI an attractive acquisition target.
- A strong deposit franchise. Deposits provide funding and an established customer base that a fintech would otherwise need to build. For example, in the OppFi-BNCCORP transaction, the target's approximately $1B deposit base was specifically identified as a strategic benefit.
- Established lending relationships. A CFI may bring underwriting expertise, knowledge of particular industries, and long-standing relationships with borrowers that complement a fintech's technology and distribution capabilities.
- A sound regulatory and compliance record. A fintech acquiring a bank is taking on a regulated institution, so the quality of its risk management, governance and compliance infrastructure matters alongside its financial performance.
- Size and infrastructure. Increase Bank illustrates how a relatively small institution can provide a regulated platform without bringing the extensive branch network or legacy infrastructure of a much larger bank.
This does not mean every CFI is a potential contender for fintechs. Strategic value will depend on what a particular buyer is trying to achieve and how well the institution’s capabilities complement its business model.
What Are the Risks for CFIs?
A fintech-led acquisition can create strategic opportunities, but it also introduces risks that may differ from a traditional bank-to-bank transaction. Boards and management teams should evaluate not only the offer price, but also the buyer’s operating model, financial capacity, regulatory readiness, and plans for customers and employees.
- Loss of control over the institution’s mission. A fintech buyer may bring a different growth strategy, risk appetite, product mix, and customer-service model. After closing, local leadership and boards may have less influence over lending priorities, deposit pricing, branch strategy, community involvement, and the pace of technology change.
- Integration and execution risk. A bank acquisition gives a fintech a charter and an operating platform, but it does not make integration simple. Core systems, data, policies, vendor arrangements, lending operations, customer support, cybersecurity controls, and compliance processes may all need to be aligned. A poorly managed conversion can create disruption for customers and employees.
- Risk-management and regulatory pressure. A buyer may be experienced in technology or digital lending but less experienced in operating a regulated depository institution. Material changes to products, underwriting, third-party relationships, data use, or growth plans can increase operational and compliance demands. The combined organization must demonstrate that its governance, capital, liquidity, consumer-protection, and risk-management frameworks can support its strategy.
- Employee, customer, and community disruption. A buyer focused on digital delivery or national scale may reduce the role of branches, centralize functions, alter relationship-management models, or change product offerings. That can affect employee retention, customer confidence, and the local relationships that have supported the CFI’s franchise.
- Valuation and deal-certainty considerations. A strong offer is not only about price. Management and directors should assess the buyer’s financing, transaction structure, regulatory path, post-close ownership, and any stock or contingent consideration. A buyer may value deposits, a charter, or technology infrastructure highly while placing less value on the CFI’s local franchise or relationship-banking model.
Key Steps to Assess Your Options
1. Assess your strategic value. Look beyond assets and earnings to understand what another FI or fintech might actually be acquiring: deposits, customer relationships, lending expertise, payment capabilities, technology, geographic reach, and regulatory infrastructure.
2. Consider the alternatives. An acquisition is only one possible strategic outcome. CFIs can also remain independent, pursue traditional bank M&A, develop fintech partnerships, invest in technology, or strengthen their position as a specialist financial services provider.
3. Identify gaps. Consider your institution from a potential buyer's perspective. Are there weaknesses in technology, deposits, loan concentrations, succession planning, compliance, or operational infrastructure that could reduce strategic value?
4. Strengthen areas of weakness. Whether a CFI remains independent or eventually enters a transaction, strengthening its deposit franchise, technology, risk management, and customer relationships can improve resilience and competitiveness.
Fintech-led acquisitions may remain a small part of the broader M&A market, but they illustrate how the definition of a CFI’s strategic value is changing. For CFIs, understanding what a technology-driven buyer might value can be useful even when selling is not part of the plan. The exercise can help management identify what makes the institution distinctive, where it needs to invest, and which strategic options it wants to preserve.